All Categories
Featured
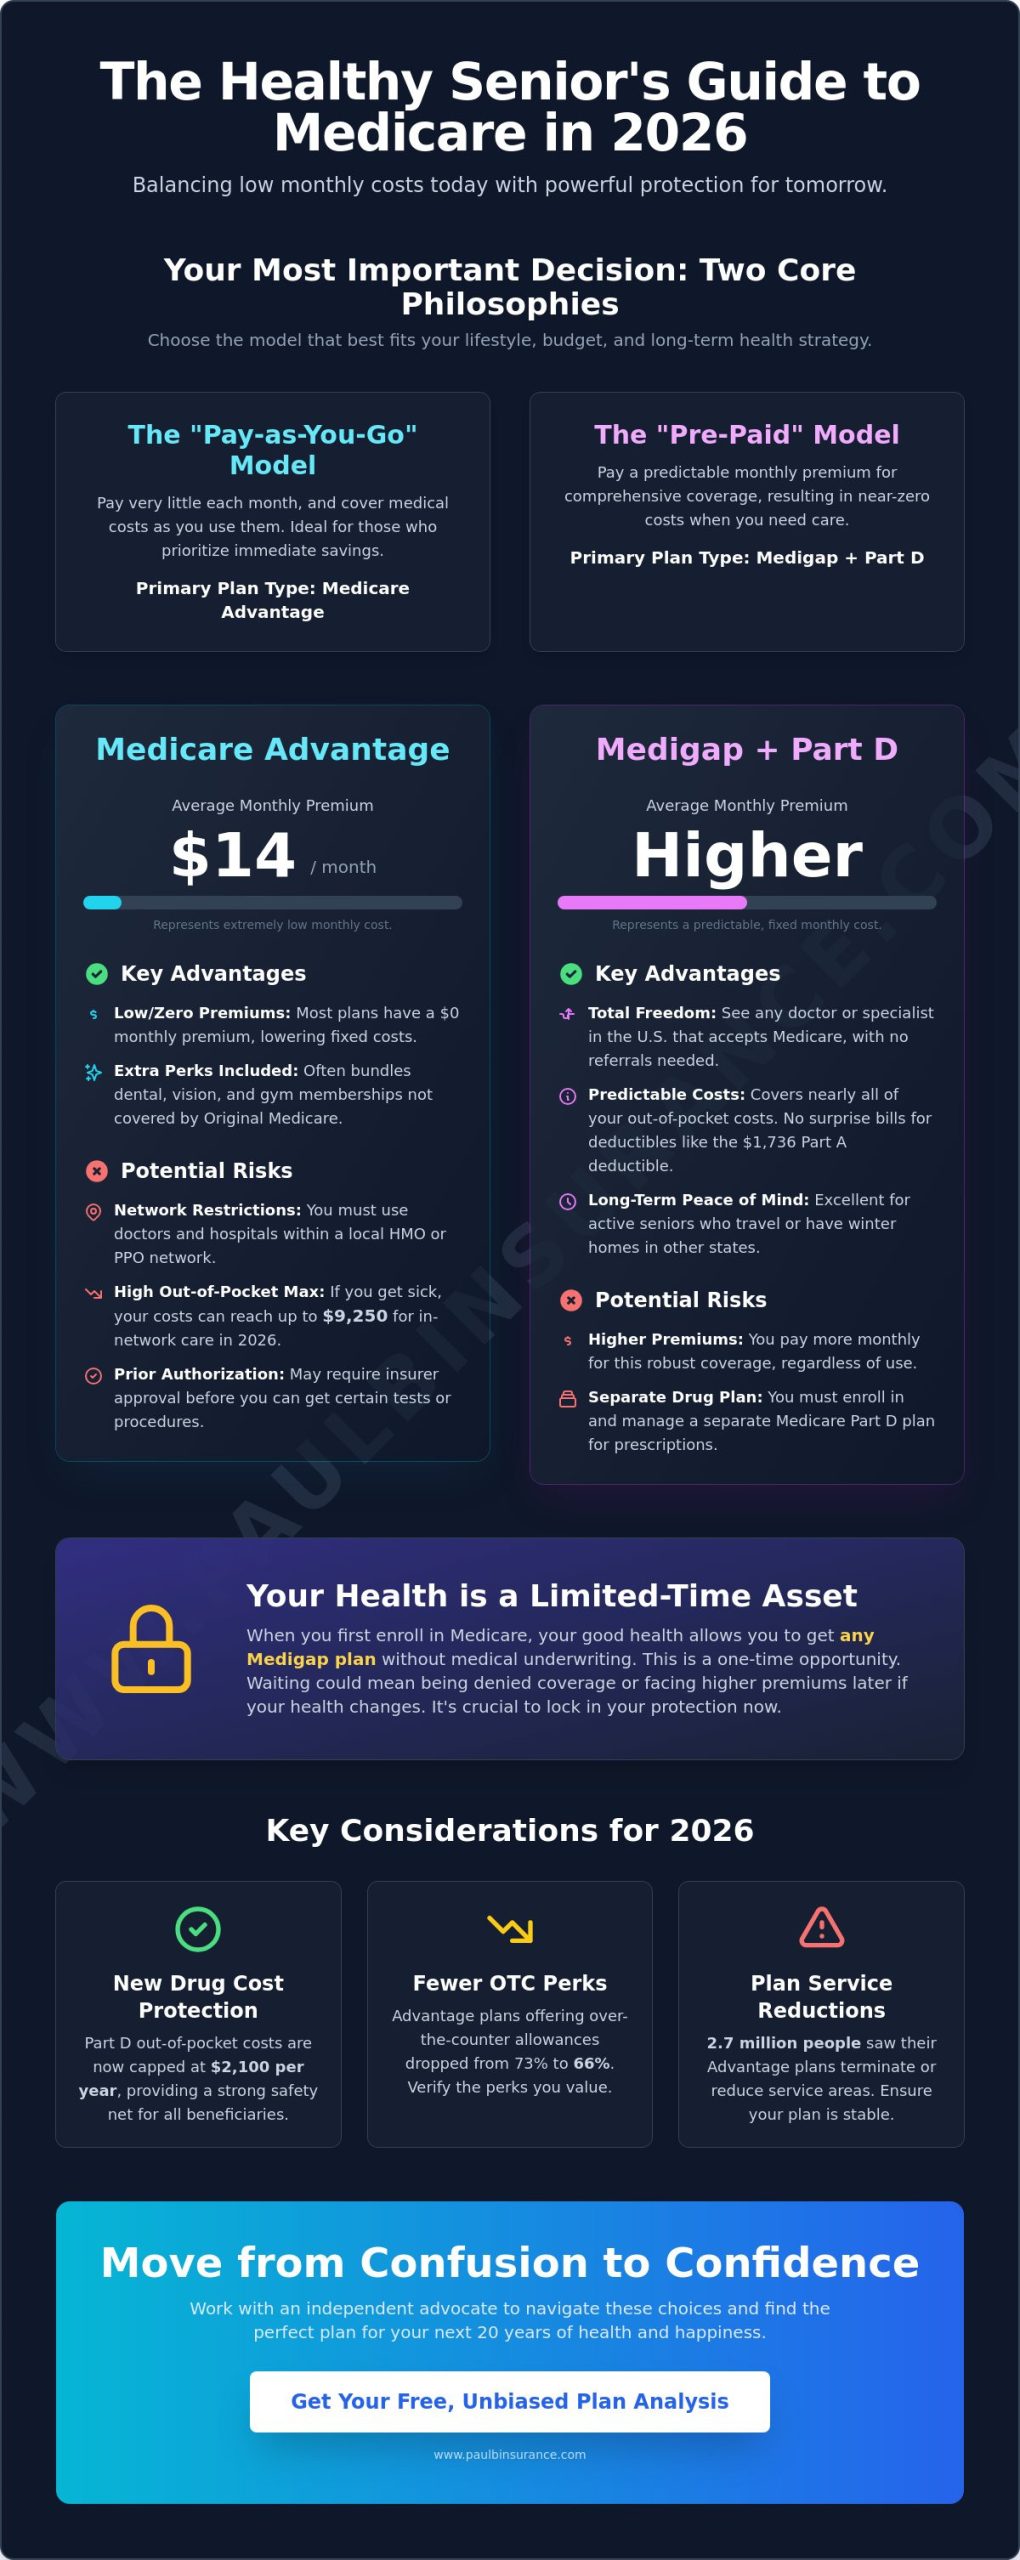
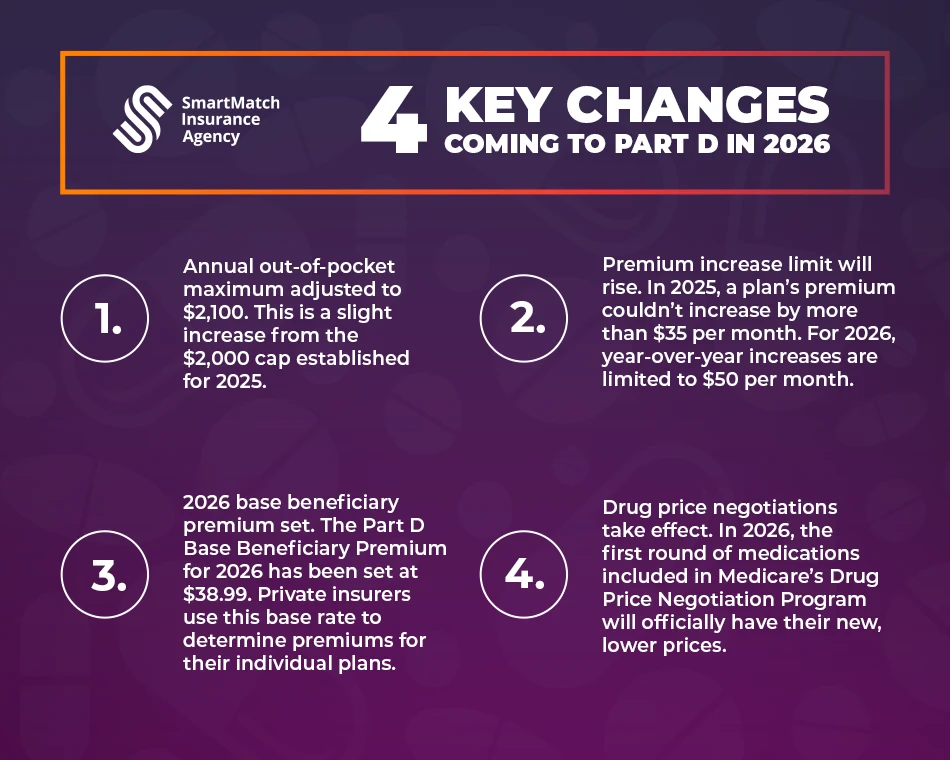
Key Strategies for 2026 Medicare Part D Enrollment
The cost of an indexed universal life insurance policy varies, depending on aspects like your age, where you live, your health and the coverage amount you select. According to one quote, a healthy, nonsmoking 34-year-old female might pay in between$71 and $96 a month for an indexed universal life policy, assuming$250,000 of protection. The very same individual may pay$32 to$44 a month for a term life policy and in between $177 and$245 per month for a whole life policy.
Insurance in Buena Park CA
It's likewise an excellent choice if you think you'll need to change your premium and survivor benefit. You may not require a life insurance policy after you've paid off your debts and conserved for your big financial goals, like retirement and your kid's college education. In these circumstances, a term life insurance coverage policy with a separate retirement fund and other cost savings lorries may offer what you require, and at a lower cost tag. An independent representative can stroll you through your choices to discover the best protection quantity for the very best price with a credible insurance provider. As soon as you have a couple of quotes, you ought to: Compare coverage limitations, estimated regular monthly payments and administrative or management fees that include each policy. Select a policy and an insurance provider. The business may ask you to go through a phone interview or medical examination. Once authorized, start paying premiums on a regular basis. Indexed universal life insurance provides long-term protection with a death benefit and a cash value that grows based on underlying financial investments. You can either allocate the money worth portion in a fixed account, an indexed account or both.
These are complex policies that might need some oversight, so it's essential to deal with a monetary organizer or another licensed specialist before picking one. You might also compare IUL policies against other kinds of life insurance coverage to see what works best for your situation. Depending on who you ask, indexed universal life (IUL) insurance coverage is either an effective wealth-building strategy or an overly complicated insurance coverage item that assures more than it provides. The truth might lie somewhere in the middle . An IUL is very first and foremost a life insurance policy. Like other permanent life insurance coverage products, it can supply long-lasting coverage and build money value gradually. Rather of making a set interest rate, it's tied to the performance of a stock market index, such as the S&P 500. Here's how indexed universal life insurance works, who it may be a great fit for, and what to understand before purchasing a policy. Indexed universal life insurance is a kind of permanent life insurance that integrates a survivor benefit with a cash value account. Unlike whole life insurance coverage, which credits your cash worth at a fixed rate of interest, an IUL ties your money value growth to the performance of a market index, such as the S&P 500, the Dow Jones Industrial Average, or the Nasdaq Composite(hence the "indexed"part of the name). Every premium payment you make for a UIL policy is normally split 3 ways: Similar to all money value life insurance, you might be able to obtain versus your balance, withdraw funds, or perhaps use it to help cover future premiums. Instead, the insurer uses the index as a benchmark to determine just how much interest to credit to the cash value part of your policy. If the index performs well, your money value may earn more interest. If the index has a bad year, your credited interest may be lower(often even 0%), depending on your policy's terms. If your policy credits the.
The Complete Guide to 2026 Medicare Options
full 10%, your money value might earn about $5,000 in interest before costs and policy charges. When you hear that an IUL's cash worth is connected to the stock market, you might presume you'll earn whatever the market earns. But that's rarely how it works. A cap is the maximum interest your policy can make during a crediting duration. You can normally find your cap in your policy illustration or files.
Even though the index increased by 15 %, your policy would only be credited 10 % before fees and other policy charges. If your policy has an 80 %participation rate and the index increases 10%, you would receive 8%interest (80%of the index's gain), presuming no cap restricts the return. Many indexed universal life policies let you select between 2 types of death benefits: Your recipients get a fixed death benefit throughout the life of the policy.

Latest Posts

Strategies for Maximum Financial Security Using Life Insurance

Planning Expense and Burial Insurance Options
Key Strategies for 2026 Medicare Part D Enrollment